
Does Health Insurance Cover Gynecomastia Surgery? What Makes a Claim Succeed
Gynecomastia surgery may be covered by health insurance in some cases, but coverage is not automatic. Most health insurance policies consider male breast reduction a cosmetic procedure unless there is sufficient medical evidence showing that surgery is necessary to treat a diagnosed health problem. The success of a claim can depend on your policy wording, medical records, diagnostic reports, symptoms, treatment history, and whether pre-authorisation was obtained before surgery.
At Elegance Clinic, Surat, Dr. Ashutosh Shah, a board-certified plastic surgeon with 22+ years of experience in plastic and cosmetic surgery, evaluates patients with gynecomastia to determine the nature of the chest enlargement and the appropriate treatment approach.
If you are considering gynecomastia surgery and want to use health insurance or mediclaim, understanding the difference between cosmetic treatment and medically necessary surgery is important before beginning the claim process.
Why Do Most Policies Classify Gynecomastia Surgery as Cosmetic by Default?
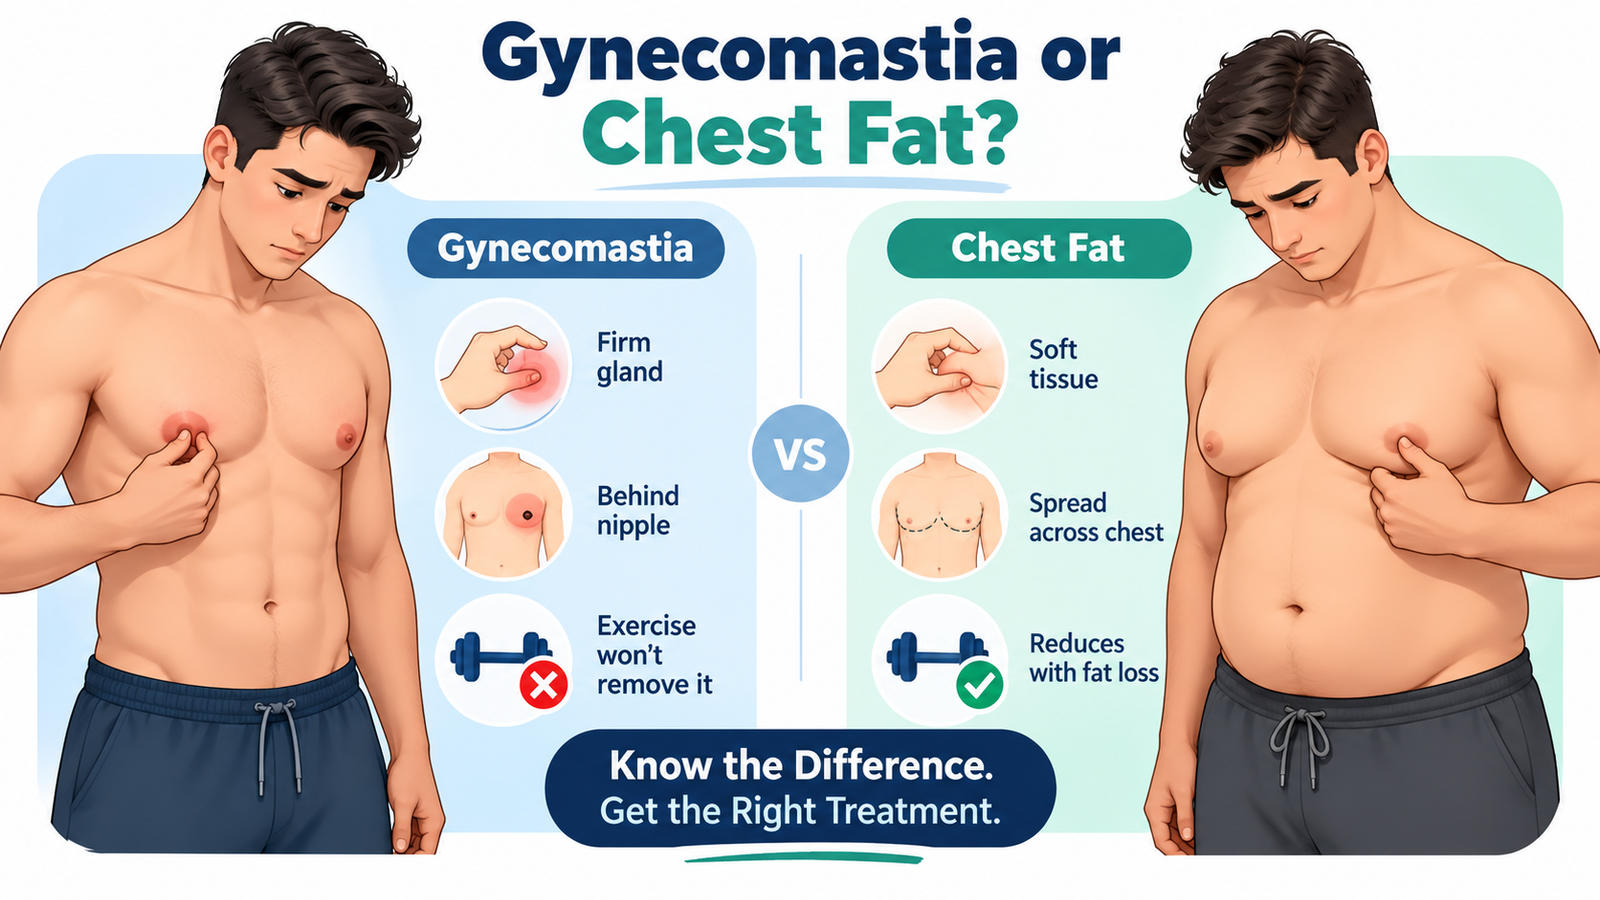
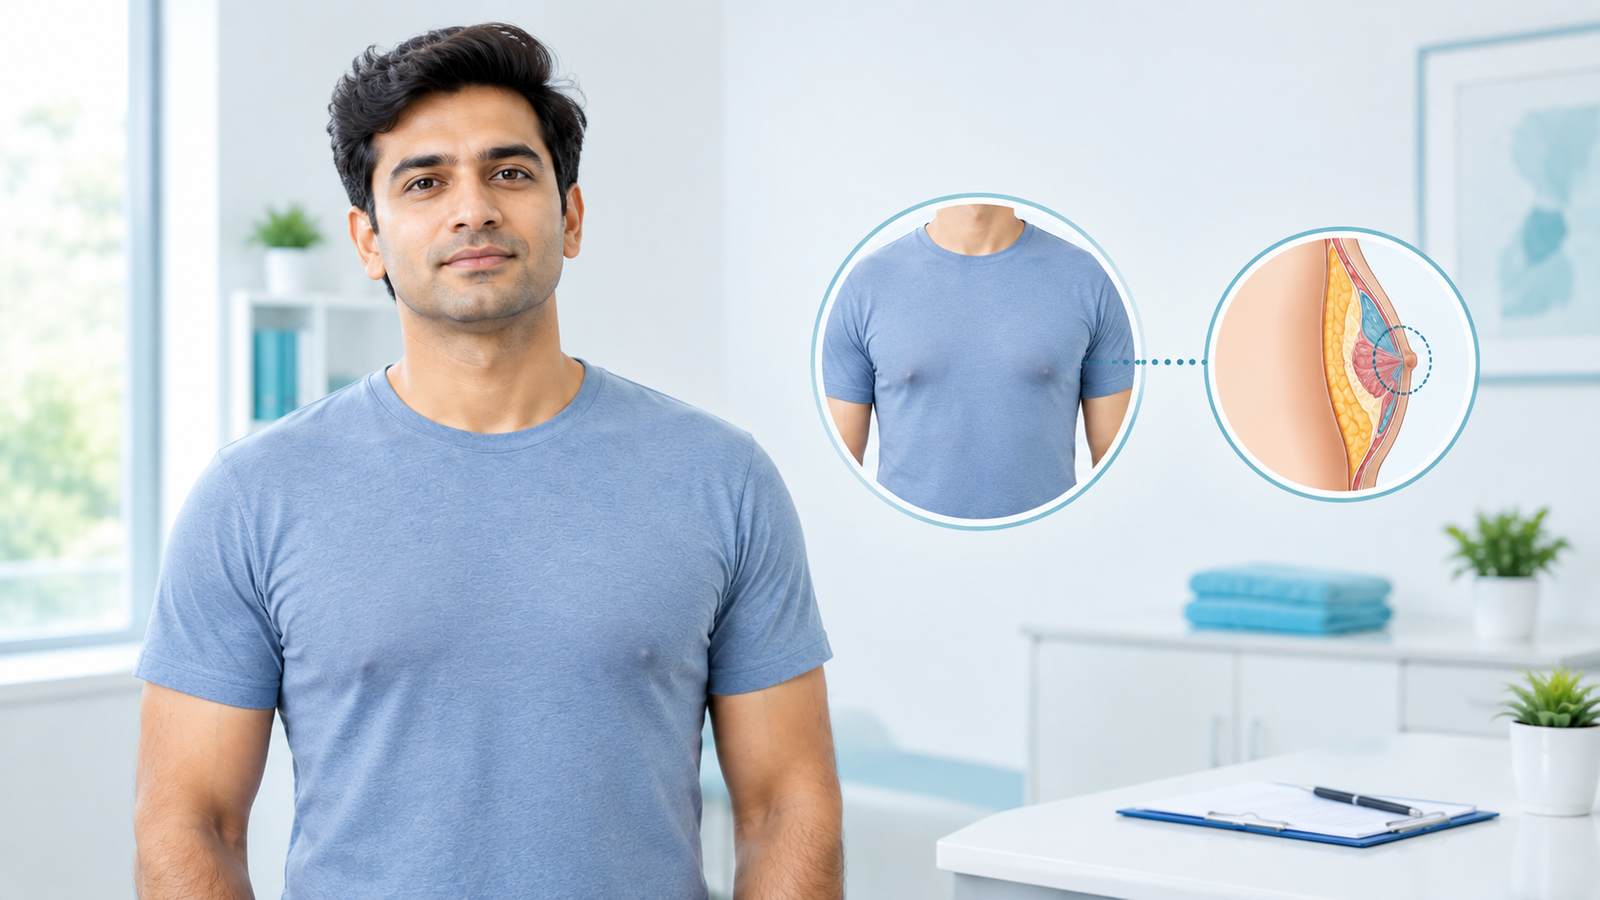
Gynecomastia is the enlargement of male breast tissue. It may occur due to hormonal changes, certain medicines, underlying health conditions, or other factors.
However, not every case requires surgery for medical reasons.
When male breast reduction is performed mainly to improve chest appearance or body contour, an insurer may classify the procedure as cosmetic or aesthetic surgery. Many health insurance policies exclude procedures performed solely for cosmetic improvement.
This does not necessarily mean that every gynecomastia operation will be excluded.
The circumstances may be different when a patient has a diagnosed medical condition accompanied by persistent symptoms or other clinical indications, and the treating surgeon recommends surgery as medically necessary.
Therefore, the reason for undergoing surgery can become an important part of the insurance assessment.
Which Grounds Make the Surgery Medically Necessary?
There is no single rule that guarantees that gynecomastia surgery will be considered medically necessary. The insurer will usually assess the patient's individual condition and the terms and exclusions of the policy.
Medical necessity may be considered when there is documented clinical evidence such as:
- Persistent pain or tenderness in the breast or chest
- Significant glandular enlargement confirmed during medical evaluation
- Symptoms that continue despite appropriate conservative management
- An underlying medical condition associated with gynecomastia
- Functional problems related to significant breast enlargement
- A surgeon's documented recommendation that treatment is medically required
- Diagnostic findings supporting the diagnosis and proposed treatment
The important point is that the claim should be supported by medical evidence, rather than only stating that the patient is unhappy with the appearance of the chest.
During a gynecomastia consultation at Elegance Clinic, Dr. Ashutosh Shah may evaluate whether the enlargement is caused predominantly by glandular tissue, fatty tissue, or a combination of both. Further investigations may be advised when clinically required to understand possible contributing factors.
Is Gynecomastia Surgery Cosmetic or Medical?
It can potentially be either.
If surgery is performed only for aesthetic chest contouring, it is generally more likely to be treated as cosmetic.
If a physician documents a medical problem and recommends surgery because of clinical symptoms or another medically significant reason, the insurer may evaluate the procedure differently.
However, even when a surgeon considers surgery medically appropriate, insurance approval is not guaranteed. The final decision is made according to the patient's policy and the insurer's assessment.
Which Documents Decide the Claim?
Documentation is one of the most important parts of a medical claim for male breast reduction.
An insurer needs evidence explaining the diagnosis, symptoms, previous management, and the reason surgery has been recommended.
Incomplete records can make it more difficult for an insurance company to determine whether a procedure falls within the policy's coverage.
Claim Documentation Checklist
| Document | Who issues it | Why the insurer may ask for it |
|---|---|---|
| Medical consultation records | Treating doctor/surgeon | Establishes diagnosis and clinical history |
| Gynecomastia diagnosis | Treating specialist | Confirms the medical condition |
| Clinical examination findings | Surgeon | Documents the extent and characteristics of the condition |
| Diagnostic reports | Diagnostic centre/hospital | Supports the diagnosis or investigates possible causes |
| Prescription and treatment history | Doctor/hospital | Shows previous medical management where applicable |
| Recommendation for surgery | Treating surgeon | Explains why an operation has been advised |
| Medical necessity letter | Treating doctor/hospital | Provides clinical justification for treatment |
| Hospital estimate | Hospital | Gives the insurer expected treatment costs |
| Pre-authorisation form | Hospital/insurer | Requests approval before a planned cashless procedure |
| Policy and insurance details | Patient/insurer | Allows verification of coverage, exclusions, and conditions |
| Discharge summary | Hospital | Records treatment performed during hospitalisation |
| Final bills and receipts | Hospital | Required when processing eligible expenses or reimbursement |
The exact documents needed for a gynecomastia insurance claim can differ between insurers.
Patients should therefore ask their insurer or third-party administrator (TPA) for the current documentation requirements before treatment.
Is Pre-Authorisation or Reimbursement More Likely to Succeed?
For planned surgery, obtaining clarity from the insurer before the procedure is generally preferable to assuming that reimbursement will be available afterward.
Pre-authorisation
For an eligible cashless treatment at a network hospital, the hospital can submit a pre-authorisation request containing information such as:
- Diagnosis
- Symptoms and medical history
- Proposed procedure
- Treating doctor's recommendation
- Supporting investigations
- Estimated treatment cost
The insurer or TPA then reviews the request according to the policy.
They may approve it, request additional documents, approve only certain eligible expenses, or decline the request.
Pre-authorisation can therefore give the patient more clarity about the insurer's position before proceeding with planned treatment.
Reimbursement
In a reimbursement claim, the patient generally pays the hospital and subsequently submits eligible expenses and supporting documents to the insurer.
A reimbursement claim still has to satisfy all policy conditions.
Paying for surgery first does not mean that the insurer is obligated to reimburse it afterward.
For this reason, patients considering gynecomastia surgery should not assume that they can simply submit the bills later and receive payment.
What Can Be Done After an Insurance Claim Is Rejected?
A rejected claim does not always mean there are no further options.
The first step should be to understand the exact reason for rejection.
For example, an insurer may state that:
- The procedure falls under a cosmetic-treatment exclusion
- Medical necessity has not been sufficiently established
- Required documents are missing
- A waiting-period provision applies
- A particular policy exclusion applies
- Additional clinical information is required
The next step depends on the reason given.
If documents are missing, the patient may be able to submit additional reports or medical records. If medical necessity was unclear, the treating doctor may be able to provide a more detailed clinical explanation where appropriate.
Patients should follow the insurer's prescribed grievance or appeal process if they believe the claim has been assessed incorrectly.
Keep copies of the policy, pre-authorisation request, medical reports, bills, correspondence, and rejection communication. These records can be useful when seeking clarification or filing an appeal.
Does the Waiting Period Apply to Gynecomastia Surgery?
It depends on the health insurance policy.
Policies can contain different waiting periods, exclusions, and conditions for particular illnesses or treatments. Whether any waiting period applies to gynecomastia treatment therefore cannot be determined from the procedure name alone.
Check the policy wording and ask the insurer to confirm the applicable provisions.
If you have recently purchased health insurance and already have diagnosed gynecomastia, additional policy conditions may also need to be considered.
Do not rely only on verbal confirmation. Where possible, obtain clarification from the insurer through its official communication channels.
Why Medical Evaluation Matters Before an Insurance Claim
Insurance documentation should begin with an appropriate medical evaluation.
Gynecomastia can have different causes, and treatment should be based on the patient's individual diagnosis rather than insurance eligibility alone.
A medical assessment can help determine:
- Whether true glandular gynecomastia is present
- Whether excess chest fat is contributing to the appearance
- Whether further investigations are required
- Whether medicines or another condition could be contributing
- Whether observation or non-surgical management is appropriate
- Whether surgery is indicated
- Which surgical approach may be suitable
With 22+ years of experience in plastic and cosmetic surgery, Elegance Clinic, Surat, assesses each case individually before recommending an appropriate treatment plan.
This assessment also creates a documented clinical record that can be relevant if insurance approval is later requested.
Understanding Gynecomastia Surgery Cost and Insurance
Even when an insurer approves treatment, this does not necessarily mean every expense associated with surgery will be paid.
Depending on the policy, patients may encounter:
- Co-payments
- Deductibles
- Room-rent restrictions
- Non-medical expenses
- Sub-limits
- Excluded items
- Limits on eligible hospital charges
Therefore, patients should consider both gynecomastia surgery cost and the amount actually eligible under their insurance policy.
Ask the insurer and hospital about estimated out-of-pocket expenses before admission whenever possible.
When Is Surgery Needed Instead of Medicine?
Not every patient diagnosed with gynecomastia needs an operation.
Treatment depends on factors such as the underlying cause, duration of the condition, symptoms, age, clinical findings, and the nature of the enlarged tissue.
In some situations, the doctor may recommend observation or management of an underlying cause.
Surgery may be considered when gynecomastia persists, and an appropriate medical evaluation indicates that an operation is the suitable treatment.
The decision about when surgery is needed instead of medicine should therefore be made after consultation with an appropriately qualified doctor.
Patients in Surat can consult Dr. Ashutosh Shah at Elegance Clinic for an individual assessment of gynecomastia and to understand whether surgical or non-surgical management may be appropriate for their condition.
Before Filing a Gynecomastia Insurance Claim
Before scheduling surgery under health insurance, patients should verify their policy carefully.
Check whether cosmetic surgery is excluded, whether medically necessary reconstructive procedures are addressed separately, whether a waiting period applies, and whether treatment needs to be performed at a network hospital for cashless benefits.
Also ask whether prior approval is required.
If insurance does not cover the procedure or only covers part of the treatment cost, patients can also ask the clinic about available payment options or EMI facilities. EMI options may help eligible patients manage the cost of gynecomastia surgery through convenient instalments rather than paying the entire amount at once. Availability, eligibility, tenure, interest, and other terms may vary depending on the payment or financing provider.
Most importantly, provide accurate information. Medical reports and insurance forms should reflect the actual diagnosis, symptoms, and clinical findings.
A cosmetic procedure should not be misrepresented as medically necessary simply to obtain insurance coverage.
Consult Dr. Ashutosh Shah for Gynecomastia Treatment in Surat
If you are concerned about enlarged male breast tissue or are considering gynecomastia surgery, a proper medical evaluation is the first step.
Dr. Ashutosh Shah is a board-certified plastic surgeon and Director of Elegance Clinic in Surat, with 22+ years of experience in plastic and cosmetic surgery. Patients can consult him for evaluation of gynecomastia, discussion of appropriate treatment options, and guidance regarding the medical documentation that may be required when approaching an insurer.
Insurance approval, however, remains entirely subject to the patient's individual policy and the decision of the insurer or TPA.
Conclusion
So, does insurance cover gynecomastia surgery? There is no universal yes-or-no answer.
Male breast reduction performed purely for cosmetic improvement is commonly excluded from health insurance. However, when gynecomastia is associated with documented medical problems and surgery is considered medically necessary, an insurer may assess the claim according to the specific policy terms.
A well-prepared claim should include a clear diagnosis, relevant medical records, supporting investigations where required, the surgeon's recommendation, and accurate documentation explaining why surgery has been advised.
For planned surgery, patients should contact their insurer and hospital before treatment to understand pre-authorisation requirements, exclusions, waiting periods and potential out-of-pocket costs.